
Financial services marketing operates within a structural paradox that continues to challenge the most sophisticated CMOs: the disconnect between the moment a piece of content influences a buyer and the moment a multimillion-dollar deal reaches its final execution. In an industry where trust and regulatory compliance are the primary currencies, the sales cycle for enterprise-level financial products is rarely a linear progression. Instead, it is a prolonged, multi-stage endurance test that often spans several quarters, rendering traditional, last-touch attribution models obsolete and potentially misleading.
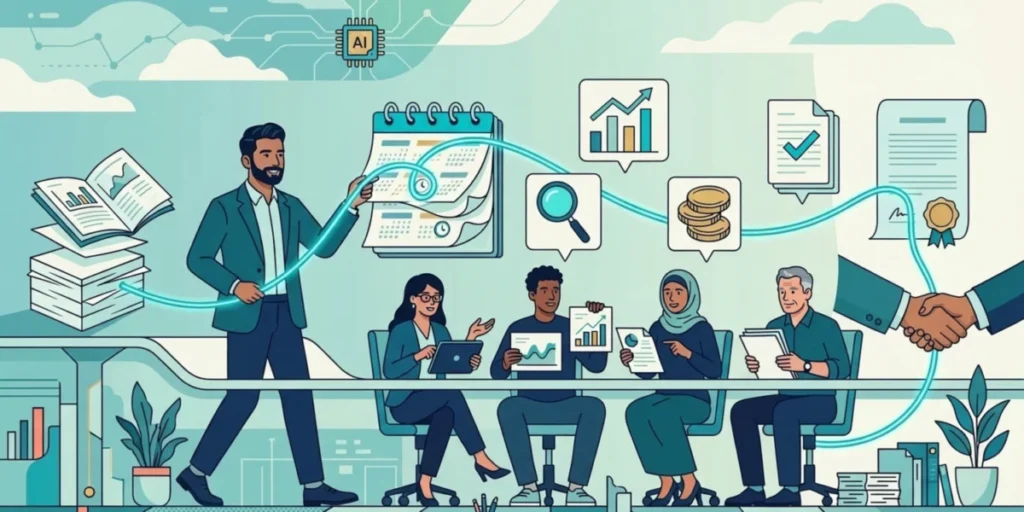
The core of the problem lies in the structural mismatch between standard marketing analytics and the reality of the modern B2B buying committee. When a procurement lead, a risk officer, and a CFO are involved in a decision, their engagement with educational content is often asynchronous, fragmented, and frequently occurs outside the direct line of sight of conventional lead-tracking software. To bridge this gap, financial services firms are increasingly moving away from simple lead-generation metrics toward holistic, multi-stakeholder measurement frameworks that better reflect the complexity of long-cycle institutional sales.
The Anatomy of the Buying Gap
The standard B2B sales funnel, once characterized by a clean handoff from marketing to sales, has been disrupted by a more complex reality. Recent industry data from Gartner underscores the severity of this shift, revealing that B2B buying groups now typically range from five to 16 stakeholders, representing up to four distinct functional areas within an organization. In the context of a financial services procurement—such as selecting a new treasury management system or a complex risk mitigation platform—the decision-making process is fraught with internal friction.
Research suggests that 74% of these buying teams experience significant, often "unhealthy" conflict during the decision-making process. This conflict stems from the divergent priorities of the stakeholders involved. A risk officer may prioritize the minimization of liability, whereas a CFO is focused on the immediate impact on the balance sheet and long-term payback periods. When these competing interests collide, the content that effectively navigates these objections often resides in the "dark funnel"—the phase of the journey where buyers consume information, conduct research, and form opinions before ever interacting with a sales representative.
The chronology of these deals often spans six to 18 months. An enterprise buyer might download a white paper on regulatory compliance in March, but the final contract may not be signed until the following November. During those eight months, the original white paper may never be mentioned in a sales call, yet it likely served as the foundational logic that allowed the champion within the firm to build a business case for the purchase.
Why Traditional Attribution Fails
Traditional attribution models, particularly last-touch and first-touch, were designed for e-commerce or high-velocity sales where the time from stimulus to conversion is measured in minutes or days. In financial services, these models create a distorted view of marketing effectiveness.
Last-touch attribution rewards the final step of the funnel—often a simple demo request or a contract signature—ignoring the months of intellectual labor that preceded it. Conversely, first-touch attribution over-indexes on the initial interaction, failing to account for the content that kept the account engaged through the long, arduous middle of the cycle. By ignoring the nuance of multi-stakeholder journeys, these models lead to the systematic under-investment in high-value, top-of-funnel educational assets.
Furthermore, the rise of the "rep-free" buying experience, where 61% of B2B buyers now prefer to perform their own research before engaging with a human seller, means that the most influential moments of the buyer’s journey are increasingly invisible to CRM systems. When content is consumed on third-party sites or via email sharing among team members, the tracking pixels typically used by marketing departments fail to capture the influence, leading to a massive misallocation of marketing budget toward low-impact, bottom-of-funnel activities.
Toward a Full-Journey Measurement Framework
To move beyond the limitations of current tracking, leading financial institutions are adopting a three-pronged approach to measuring content ROI:
- Account-Level Aggregation: Instead of tracking individual leads, organizations are beginning to track content engagement at the account or buying-group level. This allows marketing teams to see the collective movement of an entire firm toward a decision, even if individual stakeholders move at different speeds.
- Influenced Revenue Attribution: By mapping content engagement against the total value of closed deals, firms can begin to calculate "influenced revenue." This metric shifts the conversation from volume-based metrics like "cost per lead" to value-based metrics that align with the CFO’s priorities.
- Buying-Group Reach: This metric measures the penetration of content across different functions within a single account. If a piece of content is consumed by the risk, compliance, and finance departments, it is considered a high-value asset, regardless of whether it directly led to a form submission.
Aligning Metrics with the CFO’s Language
Financial services marketing must undergo a translation process to survive the scrutiny of the boardroom. The language of the CFO is not the language of click-through rates or page views; it is the language of capital efficiency, payback periods, and risk-adjusted returns.
When reporting to leadership, marketing teams should emphasize metrics that mirror the firm’s own investment criteria. For example, "cycle-time impact" can be used to demonstrate how accounts that engage with specific, high-intent content reach the closing phase faster than those that do not. If a firm can prove that a set of white papers or webinars reduces the sales cycle by 15 days, they are providing a tangible, financial argument for marketing spend that goes beyond the typical "brand awareness" justification.
Moreover, the "payback period" for content can be calculated by comparing the cost of content production and distribution against the accelerated velocity of influenced revenue. When marketing is framed as an investment in the efficiency of the sales team, it becomes much easier to secure the budget necessary for high-quality, expert-led content.
The Role of Regulatory-Ready Content
A unique challenge for financial services is the requirement for extreme precision and compliance. Marketing content in this sector is not merely about persuasion; it is about establishing professional credibility. As such, the production of this content often requires the involvement of CFAs, JDs, and FINRA-registered reviewers. This level of oversight, while essential for risk management, adds a layer of complexity to the production workflow that other industries do not face.
The implication for firms is clear: content that is not only high-quality but also compliant acts as a "de-risking" mechanism for the buyer. When a prospect sees that a firm has taken the time to produce a white paper that is peer-reviewed and technically sound, it lowers the perceived risk of the partnership. While this is difficult to quantify, it is a major factor in the acceleration of the sales cycle.
Conclusion: The Strategic Shift
The transition to a more sophisticated attribution model is not merely a technical upgrade; it is a cultural shift in how marketing is perceived within the enterprise. By moving away from the vanity metrics of the past and toward a model that recognizes the complexity of the modern financial services buyer, firms can unlock a more efficient and effective marketing strategy.
The data supports this shift: as 57% of sales professionals report that cycles are lengthening, the companies that thrive will be those that view content as a strategic asset for navigating the multi-person decision-making process. By mapping the journey, aligning sales and marketing on a single definition of influence, and speaking the language of the CFO, financial services firms can ensure that their marketing spend is treated with the same analytical rigor as any other capital investment. The measurement gap is closing, but only for those who are willing to change how they measure the journey.