
The consumer-facing interface of a modern neobank is a masterclass in minimalist design. With just a few taps on a smartphone screen, a user can open an account, receive funds, convert currencies, execute international transfers, and manage daily spending. To the average retail consumer, banking appears entirely seamless, reducing complex financial maneuvers to a frictionless digital experience.
However, beneath this veneer of simplicity lies an intricate, high-friction labyrinth of legacy financial machinery. When a customer initiates a cross-border transaction, capital does not simply teleport from one account to another. It must navigate a fragmented ecosystem of international borders, institutional settlement windows, liquidity providers, foreign exchange (FX) desks, and local payment rails before finally landing in the recipient’s account. For neobanks scaling operations across multiple international jurisdictions, this behind-the-scenes complexity multiplies exponentially, introducing significant capital overhead, transaction delays, and operational bottlenecks.
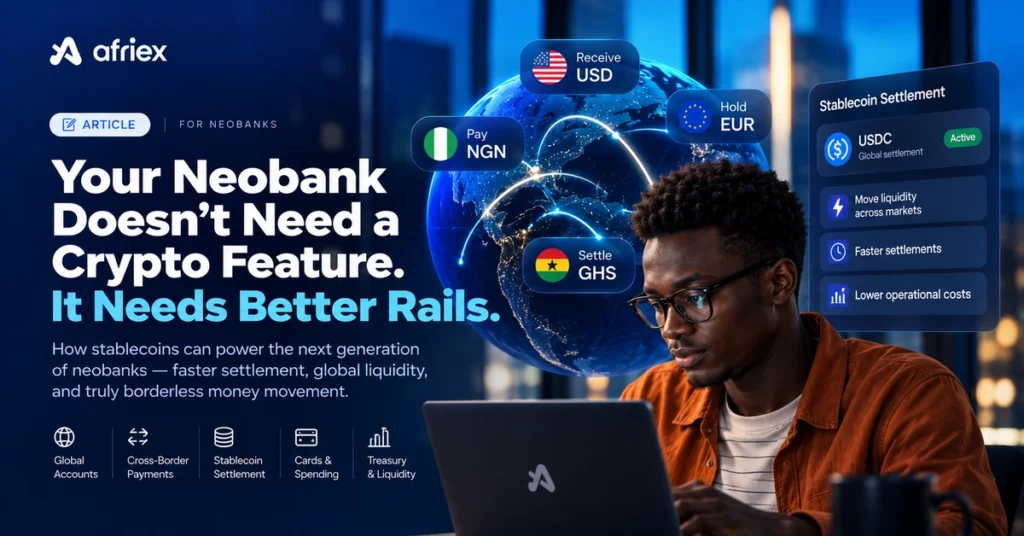
Industry observers note that a quiet architectural shift is underway to solve this structural dilemma. Rather than positioning themselves as consumer crypto platforms, the next generation of global fintech companies is increasingly integrating stablecoins—digital assets pegged to fiat currencies like the US dollar—directly into their backend execution layers. The strategic objective for these financial institutions is not to force retail users to adopt blockchain technology, but rather to leverage stablecoins as high-performance plumbing to modernize global money movement.
The Architectural Disconnect: Simple UX Versus Complex Infrastructure
To understand the current evolution of fintech, one must examine the fundamental disconnect between the front-end user experience and the back-end orchestration layer. When a user in the United States transfers one thousand dollars to a relative overseas, their mental model of the transaction is binary: the sender dispatches the funds, and the recipient collects them.
The neobank facilitating the transfer, conversely, must manage a sprawling operational workflow. This orchestration layer requires handling compliance checks, multi-currency ledger adjustments, correspondent banking relationships, and localized clearinghouse protocols. Traditional banking infrastructure, largely constructed decades before the advent of modern software development, was never engineered to operate with the speed and programmability expected by today’s digital natives.
Historically, software companies circumvented legacy limitations by abstracting complexity through Application Programming Interfaces (APIs) and cloud computing architectures. Neobanks successfully applied this philosophy to consumer-facing applications, hiding the clunky mechanics of legacy banking behind sleek interfaces. Yet, as these fintech firms scale globally, the limitations of traditional cross-border settlement rails have made back-end abstraction increasingly difficult to maintain using fiat-only architecture.
The Rise of Rail-Agnostic Financial Orchestration
To overcome these structural hurdles, emerging neobanks are adopting a rail-agnostic approach to financial infrastructure. In this new paradigm, the specific mechanism used to transport value ceases to be the defining characteristic of the product. Instead, the focus shifts entirely to the quality of the financial experience delivered to the end user.
Within this framework, a modern payment stack functions as a multi-tiered orchestration engine. At the top sits the consumer application, handling accounts, card issuing, and user-facing payments. At the bottom lies a diverse suite of settlement mechanisms, which may include traditional SWIFT banking rails, local real-time payment systems, foreign exchange liquidity pools, and blockchain-based stablecoin networks.
When a customer executes a transaction, the underlying orchestration layer dynamically selects the most efficient, cost-effective, and rapid rail available. If a stablecoin network offers instantaneous settlement at a fraction of the cost of traditional wire transfers, the system may utilize a blockchain rail for the cross-border leg of the transfer, convert the digital asset into local fiat currency via a liquidity partner, and deposit funds directly into the recipient’s local bank account. Throughout this entire journey, the customer remains blissfully unaware that distributed ledger technology was involved, experiencing only a fast, low-cost transfer.
Three Critical Pillars: Settlement, Treasury, and Global Payouts
The integration of stablecoins into neobank architecture is primarily concentrated in three high-impact operational areas: cross-border settlement, treasury management, and global payouts.
First, cross-border settlement remains the most acute pain point for international fintechs. Traditional international wires are notoriously slow, often taking multiple business days to clear while passing through a chain of intermediary correspondent banks, each of which extracts fee revenue. By routing value through stablecoins, neobanks can achieve near-instantaneous global settlement 24 hours a day, 365 days a year, bypassing banking hour restrictions and weekend delays.
Second, treasury and liquidity management pose severe logistical challenges for fintechs operating across multiple currency zones. Corporate treasury teams must constantly rebalance capital reserves across various global bank accounts to ensure sufficient liquidity is available in each market. Stablecoins offer a programmable, highly liquid instrument for moving capital between international subsidiaries, allowing treasurers to reallocate funds in minutes rather than days.
Third, global payouts—such as paying thousands of remote contractors, gig-economy workers, or international merchants—benefit immensely from hybrid settlement models. Rather than managing dozens of local banking relationships and wrestling with high failure rates on international wires, platforms can utilize stablecoin rails to execute programmatic disbursements that automatically settle into local currencies at the destination point.
Industry Evolution and the Role of Infrastructure Providers
Market analysts point out that building this type of sophisticated global payment architecture from scratch is cost-prohibitive and operationally daunting for individual neobanks. Consequently, a specialized ecosystem of B2B infrastructure providers has emerged to supply modular financial components via APIs.
Companies operating in this space—such as those developing unified liquidity and treasury management platforms like Afriex’s AFX—allow businesses to plug directly into pre-built global collections, programmable payouts, local bank accounts, and automated FX routing. By outsourcing these complex execution layers to specialized infrastructure providers, neobanks can concentrate their engineering resources on what they do best: designing intuitive user experiences and acquiring customers.
This B2B-to-B2C division of labor reflects a broader maturation within the financial technology sector. The initial wave of neobanking focused primarily on wrapping user-friendly software around traditional bank charters. The current wave is focused on rebuilding the underlying plumbing of global finance.
Implications and the Future of Global Money Movement
As financial institutions increasingly harmonize traditional banking networks with blockchain-based rails, the historic dichotomy between traditional finance and cryptocurrency is beginning to dissolve. Industry experts suggest that the future of banking will not be defined by a zero-sum war between fiat currency and digital assets, but rather by a pragmatic convergence of the two.
The implications of this convergence are profound. For consumers in emerging markets burdened by hyperinflation or restricted access to hard currencies, stablecoins integrated into mainstream neobanks provide a reliable digital dollar gateway without the friction of navigating decentralized exchanges or self-custody wallets. For businesses, the reduction in settlement times and foreign exchange leakage translates directly into healthier profit margins and enhanced operational agility.
Ultimately, the neobank of the future will not be judged by the ideological purity of its payment rails, but by its ability to move money securely, instantly, and invisibly across the globe. As competition intensifies in the digital banking sector, the institutions that successfully abstract away infrastructural complexity will command the market. For these forward-thinking neobanks, the strategic mandate is clear: success does not require introducing a complex crypto feature; it requires upgrading to superior infrastructure—and stablecoins are rapidly proving to be one of the most effective rails available.