
The modern marketing campaign in the financial services sector often resembles a high-stakes obstacle course. After two weeks of intensive preparation—finalizing creative assets, configuring landing pages, and securing media placements—the project reaches its most critical juncture: the compliance review. Yet, in many institutions, this stage remains a fragmented, manual process characterized by sprawling email chains, disjointed Slack messages, and ambiguous version control. Marketing teams frequently find themselves trapped in a cycle of confusion, struggling to track which comments have been addressed, who holds final sign-off authority, and whether the latest disclosure iteration is legally sound. By the time a campaign finally clears the regulatory gate, valuable market momentum has been lost, and the relationship between marketing and legal departments is often strained.
In the highly regulated landscape of finance, leadership often perceives compliance as a stubborn barrier to growth. However, this is rarely a failure of legal oversight; rather, it is a structural failure of workflow design. While marketing teams in unregulated industries may leverage agile, collaborative tools for rapid deployment, financial firms often attempt to apply these same casual communication methods to processes that require rigorous, audit-ready documentation. The result is a persistent disconnect that hinders scalability.
The Regulatory Landscape and the Cost of Inefficiency
The necessity for a disciplined approach is underscored by recent data from the Content Marketing Institute, which reveals that 47% of enterprise marketers identify workflow and content approval processes as a primary challenge. In the financial sector, this statistic is not merely a matter of operational efficiency; it is a significant risk factor. Regulatory bodies, including the Financial Industry Regulatory Authority (FINRA) and the Securities and Exchange Commission (SEC), demand strict adherence to standards regarding the fairness, balance, and accuracy of public communications.
The cost of failing to integrate these requirements into the workflow can be substantial. A poignant example is the case of M1 Finance, which was fined $850,000 by FINRA in 2024. The firm had engaged roughly 1,700 influencers to promote its services, resulting in over 39,400 funded accounts. Crucially, the influencer posts were not subjected to the same rigorous review process as other retail communications. Because the firm’s written supervisory procedures did not explicitly route influencer content through a registered principal, the company lacked both the required fair-and-balanced review and the systematic record-keeping necessary to satisfy regulatory mandates. M1 Finance was forced to undergo a total architectural overhaul of its review processes to ensure that every promotional communication is now approved by a registered principal before publication.
Why Traditional Content Workflows Fail
Traditional marketing workflows often treat compliance as a "final check" step—a hurdle to be cleared just before the "publish" button is pressed. This approach is fundamentally incompatible with the demands of modern financial regulations. FINRA Rule 2210, which governs communications with the public, classifies material into three specific tiers: correspondence, retail communications, and institutional communications. For retail communications, the rule generally mandates that a registered principal approve the content before its first use.
The reliance on improvised review channels—emails and chat platforms—creates three specific, recurring points of failure:
- Lack of Auditability: If a regulator requests proof of approval three years from now, a thread of fragmented emails is insufficient. Firms must be able to demonstrate exactly who approved an asset, when they approved it, and what version was authorized.
- Version Control Chaos: When multiple reviewers provide feedback simultaneously across different platforms, it becomes nearly impossible to ensure that all required disclosures were implemented in the final output.
- Delayed Feedback Loops: When legal teams are brought in at the end of the content lifecycle, they are often forced to choose between approving non-compliant content or demanding massive, costly rewrites that delay the campaign schedule.
The Five Pillars of a Compliance-First Architecture
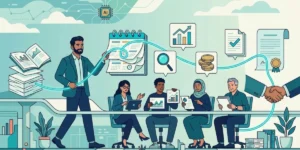
To bridge the gap between creative speed and regulatory necessity, firms must shift toward a compliance-first architecture. This design treats governance as a foundation rather than an afterthought. There are five essential components to this framework:
- Systematic Review Routing: Content should be automatically routed based on the type of asset and its inherent risk level. Low-risk content may require a single-tier review, while high-risk, complex financial claims require multi-party sign-off.
- Structured Approval Gates: The workflow must include hard stops where the system prevents publication unless the necessary digital sign-offs from authorized personnel are captured.
- Centralized Disclosure Libraries: By maintaining a repository of pre-approved language, disclosures, and templates, firms reduce the burden on reviewers. If a piece of content uses approved "boilerplate" text, the reviewer can focus their time on the unique, substantive claims of the piece.
- Immutable Audit Trails: Every interaction, change, and approval must be logged within a centralized platform, creating a chronological history that can be exported for regulatory reporting at any time.
- Automated Retention Policies: Financial firms have specific record-keeping obligations regarding the duration and storage of communications. A robust architecture automates the archiving process, ensuring that assets are stored in accordance with SEC and FINRA retention mandates.
Transitioning to a New Operating Model
True transformation requires not only better technology but a fundamental shift in the operating model between legal and marketing teams. The most successful organizations have adopted a "compliance-at-the-start" philosophy. By involving legal counsel during the brief and kickoff phases, firms can identify potential regulatory constraints early. This allows marketers to ideate within the "guardrails," rather than discovering after a week of work that their core premise is legally untenable.
Furthermore, both departments must agree on shared definitions. If marketing and legal have different interpretations of what constitutes a "performance claim" or a "tier-two asset," conflict is inevitable. Establishing a unified taxonomy for content types ensures that everyone is speaking the same language, which reduces ambiguity and speeds up the review process.
Clear Service Level Agreements (SLAs) are equally vital. Marketing departments must commit to providing complete, well-researched briefs with adequate lead time, while legal teams must provide defined turnaround windows based on the risk tier of the project. When both sides operate with predictable timelines, the adversarial "marketing vs. legal" dynamic is replaced by a collaborative partnership.
A Maturity Model for Regulated Content
Not all firms are at the same stage of operational maturity. Understanding one’s position on this spectrum is the first step toward improvement:
- Level 1 (Manual/Ad-hoc): Compliance is reactive, relying on email and manual tracking. Audit trails are non-existent or scattered.
- Level 2 (Centralized Review): The firm uses a basic routing system, but disclosures are still managed inconsistently, and the process is disconnected from the broader content lifecycle.
- Level 3 (Integrated Governance): Compliance is baked into the workflow. The firm utilizes an audit-ready platform that captures all approvals automatically, and a library of pre-approved assets is in place.
- Level 4 (Automated Compliance): The organization leverages advanced technology to automate compliance checks, utilize AI for real-time risk assessment, and provide seamless reporting for regulators.
For firms at Level 1, the most immediate gain comes from creating a central disclosure library and a standardized routing map. For firms at Level 3, the goal is to shift toward full automation, removing the friction of manual administrative steps entirely.
Conclusion: The Strategic Advantage
The transition to a compliance-first architecture is not merely an exercise in risk mitigation; it is a strategic advantage. Financial brands that master this workflow can publish more frequently, experiment with new channels, and respond to market shifts with a velocity that their less-organized competitors cannot match. By treating compliance as an integral part of the creative process rather than an external obstacle, regulated firms can build a culture of "confident publishing." In an era where regulatory scrutiny is only increasing, the ability to demonstrate governance at every stage of the content journey is the hallmark of a market leader.