
Marketing in financial services remains one of the most complex disciplines in modern B2B commerce, primarily because the gestation period between initial content engagement and the finalization of a contract often spans several fiscal quarters. This disconnect creates a significant measurement gap that traditional attribution models, designed for e-commerce or transactional sales, are fundamentally unequipped to bridge. As enterprise finance deals become increasingly sophisticated, involving larger buying committees and more rigorous risk-assessment protocols, the reliance on last-touch attribution has led to a systematic undervaluation of early-stage content marketing.
The core of the issue lies in the structural mismatch between how content is consumed and how revenue is recorded. In the current financial services landscape, a buyer might interact with a white paper or a research brief in the first quarter of the year, only for the final procurement decision to occur in the fourth. Throughout those intervening months, a complex internal ecosystem of stakeholders—ranging from risk officers and legal counsel to analysts and C-suite executives—interact with the brand’s messaging. Often, the content that actually sways the decision never appears on a sales call, leading to a "dark funnel" where the most influential pieces of collateral are credited with zero impact on the eventual closed-won revenue.
The Anatomy of a Modern Financial Buying Committee
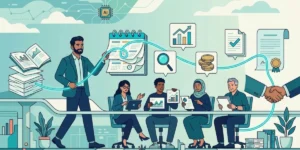
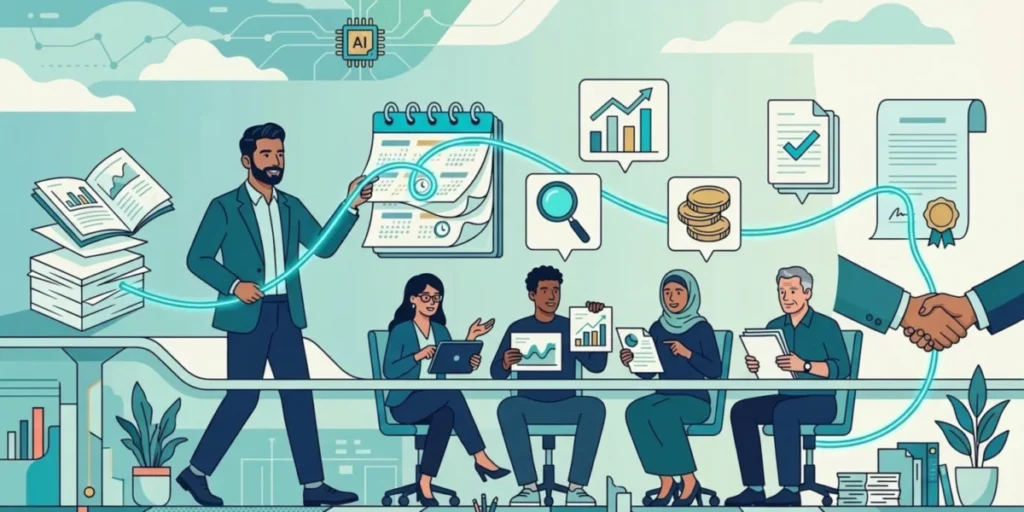
To understand why simple ROI math fails, one must look at the evolution of the buying committee. According to recent industry surveys, including data from Gartner, B2B buying groups currently range from five to 16 individuals across at least four distinct corporate functions. In a financial services context, this is particularly pronounced. A Chief Financial Officer (CFO) may have a set of performance-based requirements that are entirely distinct from those of a procurement manager or a lead data analyst.
These stakeholders rarely arrive at a consensus quickly. Gartner’s 2025 research indicates that 74% of B2B buying teams experience "unhealthy conflict" during the decision-making process. This conflict is often driven by competing departmental priorities—a controller may prioritize cost-efficiency and risk mitigation, while an operations manager may prioritize integration speed and technical agility. Content that effectively addresses these friction points early in the journey is invaluable, yet because it does not result in a direct demo request or lead form submission, it is frequently ignored by standard CRM-driven attribution tools.
The Erosion of Traditional Attribution Models
The standard metrics used by marketing teams—specifically first-touch and last-touch attribution—are increasingly obsolete in the context of long-cycle finance deals. Last-touch attribution, which rewards the final interaction before a signature, inherently favors sales collateral or pricing pages, ignoring the months of educational nurturing that enabled the deal to reach the final stages. Conversely, first-touch attribution over-indexes on initial awareness, ignoring the reality that a lead may have been "nurtured" by a dozen different assets before the committee reached a decision.
Furthermore, a significant portion of the buyer’s journey now occurs off-platform. Research confirms that approximately 61% of B2B buyers now prefer a rep-free buying experience, conducting their own independent research, peer reviews, and search queries before engaging with a sales representative. When these buyers consume content on third-party sites, industry forums, or through internal peer-to-peer sharing, the marketing team’s internal tracking tools remain blind to these interactions. Consequently, the "influence" of high-quality content is often untracked, leading to a scenario where budget is cut from the very assets that are driving the most significant pipeline movement.
Developing a Full-Journey Measurement Framework
To rectify this, marketing leaders in financial services must shift toward a multi-stakeholder, account-based measurement model. This framework prioritizes the "buying group" over the "individual lead." By tracking content engagement across the entire account, organizations can begin to see a more accurate picture of how different pieces of content influence the broader committee.
The implementation of this framework requires three strategic pillars:
- Unified Data Integration: Combining CRM data with intent signals and content analytics to create a "surrogate" map of the buyer’s journey.
- Standardized Attribution Logic: Establishing a consensus between sales and marketing on how to weight different stages of the funnel before reporting results to executive leadership.
- Outcome-Based Reporting: Moving away from volume-based metrics like "page views" and "downloads" toward value-based metrics that resonate with financial decision-makers.
Metrics That Resonate with the C-Suite
When presenting to a CFO, marketing teams must speak the language of investment and risk. Raw traffic statistics hold little weight in a boardroom focused on capital allocation. Instead, metrics such as "Content-Influenced Pipeline" and "Influenced Revenue" provide a direct line between marketing spend and financial outcomes.
"Buying-group reach" is another critical indicator of program health. This metric measures how many distinct functions within a target account have interacted with the brand’s content. If a company is targeting a bank, for example, the content team should monitor whether they have successfully engaged both the IT security department and the finance office. If the content is only reaching one, the organization is exposed to the risk of rejection from the other stakeholders.
"Cycle-time impact" offers a further layer of sophistication. By analyzing whether accounts that engage with deep-funnel content—such as case studies, ROI calculators, or compliance documentation—close faster than those that do not, marketing teams can demonstrate that their content is a catalyst for operational efficiency. In a market where 57% of sales professionals report that sales cycles are lengthening, proving that content can accelerate the "time to close" is a powerful argument for increased marketing investment.
Implications for Regulatory and Compliance Environments
Financial services marketing is unique due to its heavy regulatory burden. Content cannot simply be persuasive; it must be accurate, compliant, and defensible. This requirement adds an extra layer of difficulty to measuring ROI, as the process of creating "compliant" content—involving CFAs, MDs, JDs, and FINRA-registered reviewers—is resource-intensive.
The implication is clear: because the cost of creating high-quality, compliant content is higher than in other industries, the need for accurate measurement is even more acute. If a firm spends significant capital ensuring that a white paper is legally sound and factually precise, they must be able to justify that spend by showing its impact on the bottom line. Failure to do so risks characterizing the entire content program as a cost center rather than a revenue-generating asset.
The Road Ahead: Strategic Alignment
The path toward accurate ROI reporting begins with mapping the journey in a way that respects the reality of the multi-month sales cycle. Organizations must stop viewing the lead as a static entry in a database and start viewing the account as a dynamic group of individuals who are all consuming content at different times for different purposes.
Ultimately, the goal is to align marketing reporting with the same analytical rigors used by the finance department to evaluate any other capital project. By focusing on payback periods, revenue influence, and account-level engagement, marketers can elevate their status from service providers to strategic partners. As the industry continues to evolve, those who can successfully bridge the measurement gap will be better positioned to secure the budgets necessary to fuel long-term growth in an increasingly competitive and complex financial landscape. The tools and frameworks exist to make this shift; the primary challenge remains the organizational willingness to abandon legacy reporting for a model that reflects the true, complex nature of the modern financial decision-making process.